
Valuation Trend in European Venture Capital in 2026
Quick Answer
Explore the 2026 valuation trends in European venture capital. Learn about market challenges and investor strategies.
European venture capital is under real strain. Capital from VC firms has not kept pace with founder demand for funding, pushing valuations down and squeezing fund returns. VCs are responding by tightening due diligence, adopting AI-driven tools, and cutting operational slack wherever they can find it. What follows is a factual account of where European VC valuations stand and what is driving the current pressure.
The Bid-Ask Spread is Reversing
Founders want more than the market is willing to pay. That gap – between what founders believe their SMEs are worth and what limited partners (LPs) will fund – has widened to the point where deal flow is stalling. Founders feel undervalued; LPs are calling early-stage businesses overvalued. Neither side is entirely wrong. The practical consequence: mergers and acquisitions (M&A) and private equity deals are expected to see an uptick in 2024 as the two sides search for middle ground.
Valuations are Facing Downward Pressure
The standoff between founders and LPs is not just a pricing dispute. It changes behaviour on both sides. Investors are pulling back to profitable-first mandates – fewer moonshots, more near-term margin visibility. Cost reduction and tighter operational efficiency have become the headline criteria in pitch meetings that would have sailed through on growth metrics two years ago. SMEs seeking capital right now face a different kind of scrutiny than their predecessors did.
VC Funds Experience Temporary Negative Returns
In 2023, VC funds reported multiple negative returns for the first time in over five years. Experienced VCs treat this as a natural correction; for newer entrants, it is disorienting. Getting through this environment depends on two things: solid investor relations so LPs stay patient, and real data analysis capacity so fund managers can back decisions with evidence rather than sentiment.
VC Due Diligence Gains Importance
The loose due diligence that characterised the 2021-2022 spending spree is over. VCs are now returning to traditional benchmarks – audited financials, unit economics, reference checks, comparable transaction data – before committing capital. Patient funds with structured assessment processes will produce better vintage returns than those who chased speed. The shift rewards discipline.
The European VC Market in 2024
2023 was a materially weaker year for European VC. The combination of the war in Ukraine, global supply chain disruption, rising interest rates, persistent inflation, and recession risk pulled deal volume and invested capital down sharply. Late-stage companies took the worst of it: valuations at growth and pre-IPO stages fell faster than seed. Early-stage rounds held up somewhat better, partly because base valuations were lower and partly because seed investors have shorter decision cycles.
Fundraising Decline and Shift in Exit Activity
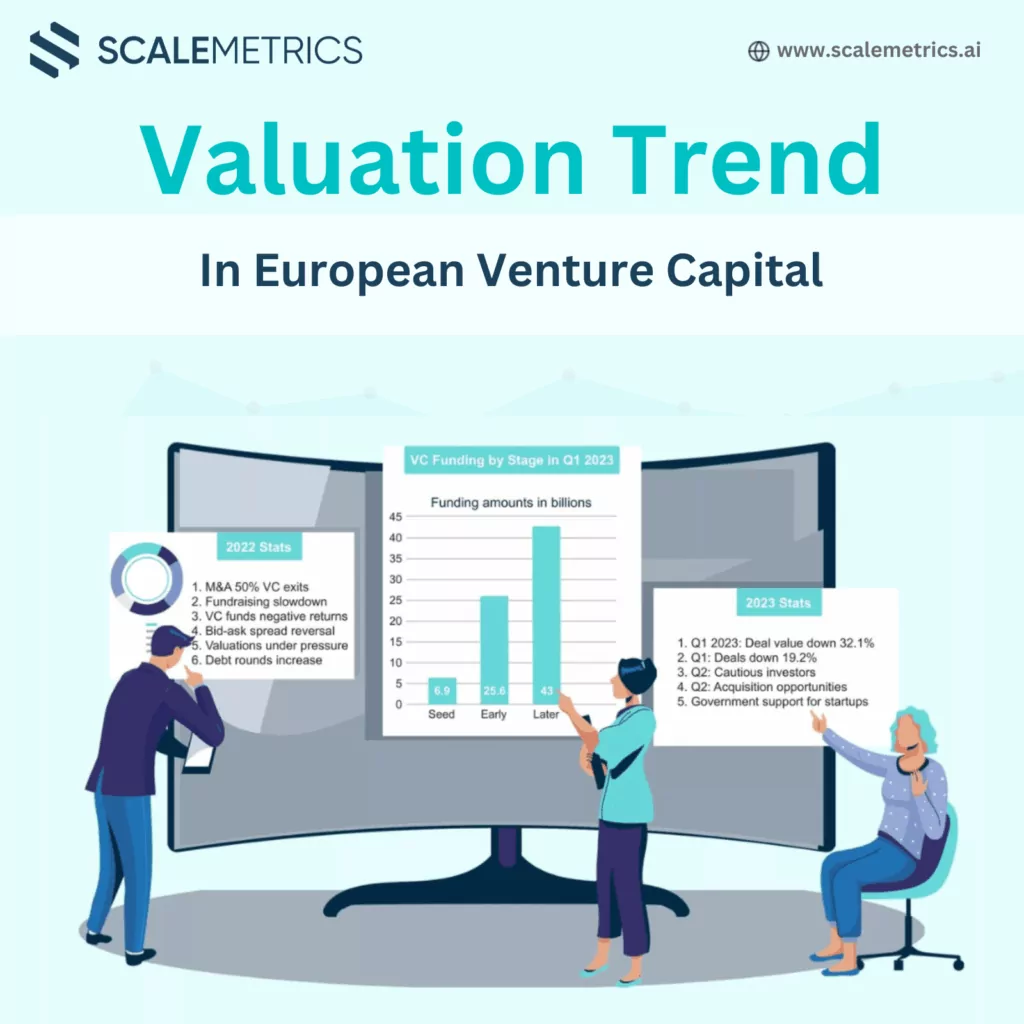
Fundraising slowed significantly in the second half of 2023 as market uncertainty made LP commitments harder to secure. Exit activity dropped even more sharply. M&A came to account for 50% of VC-backed exits – a level not seen in years. SMEs that might have held out for an IPO window chose the certainty of an acquisition by a well-capitalised strategic buyer instead. That shift matters for valuation benchmarks, because M&A exits are negotiated differently than public market liquidity events.
Q1 2024: Decline in Deal Activity and Fundraising
European venture deal value decreased by 32.1% quarter-over-quarter in Q1 2024, with the number of deals falling 19.2% over the same period. High inflation and tightening monetary policy are the direct causes: both reduce investor appetite to deploy capital and raise the return hurdle for equity investments. Debt rounds are expected to become more common alongside equity rounds as a result, and layoffs and cost reductions inside portfolio companies are likely to follow.
Chart: European Venture Deal Value (Q1 2023 – Q1 2024)
| Quarter | Deal Value (EUR billions) | Number of Deals |
|---|---|---|
| Q1 2023 | 15.2 | 900 |
| Q2 2023 | 13.0 | 850 |
| Q3 2023 | 12.5 | 800 |
| Q4 2023 | 10.3 | 750 |
| Q1 2024 | 7.0 | 600 |
Outlook for Q2 2024
Q2 2024 is expected to be another challenging quarter for VC investment in Europe. Investors will remain cautious, with emphasis on testing portfolio business models for resilience and extracting cost reductions where possible. On the other side of that caution: well-capitalised corporates see the same conditions as an acquisition window. Governments may step in with additional support for SMEs. Non-core carve-outs and bolt-on deals are likely to increase if market pressure holds.
Technology Adoption in VC Firms
The market correction has accelerated technology adoption inside VC firms. AI and machine learning are now standard tools in the toolkit rather than experiments:
1. Improve Due Diligence: AI can analyze vast amounts of data quickly, identifying potential red flags and opportunities more efficiently than traditional methods. 2. Enhance Deal Sourcing: Machine learning algorithms can identify promising startups by analyzing market trends and startup performance metrics. 3. Optimize Portfolio Management: AI-driven tools can help VCs manage their portfolio companies more effectively, providing insights into performance and suggesting improvements.
Impact of Economic Factors on VC Valuations
Three macroeconomic forces are doing most of the damage to European VC valuations right now:
1. Inflation: High inflation rates increase the cost of capital, making investors more cautious and leading to lower valuations. 2. Interest Rates: Rising interest rates make debt financing more expensive, which can reduce the amount of capital available for equity investments. 3. Geopolitical Uncertainty: Ongoing conflicts and geopolitical tensions create uncertainty, affecting investor confidence and leading to more conservative valuations.
Strategies for Startups to Navigate the VC Landscape
SMEs seeking capital in this environment need a different playbook than the one that worked in 2021. Four priorities stand out:
1. Focus on Profitability: With valuation under pressure, demonstrating a clear path to profitability can make a startup more attractive to investors. 2. Cost Management: Implementing cost-cutting measures and improving operational efficiency can help startups survive funding shortfalls. 3. Strong Investor Relations: Maintaining transparent and proactive communication with investors can build trust and improve funding prospects. 4. Exploring Alternative Funding Sources: In addition to traditional VC funding, startups should consider alternative sources such as debt financing, crowdfunding, and strategic partnerships.
Government Support for Startups
European governments are not sitting out this correction. Several categories of support are available to SMEs that qualify:
1. Grant Programs: Providing non-dilutive funding to help startups weather economic challenges. 2. Tax Incentives: Offering tax breaks and incentives to encourage investment in startups. 3. Public-Private Partnerships: Collaborating with private sector entities to provide funding and resources for startups.
Conclusion
European VC in 2024 is a market under compression. Valuations face downward pressure accelerated by interest and inflation rates, and VC funds temporarily experience negative returns. Rigorous due diligence, technology adoption, and operational discipline are the levers that let investors and SMEs stay functional in an uncertain environment. Tracking the data – deal counts, fund returns, exit mix – is not optional; it is the basis for any informed funding or investment decision in this cycle.
Related Resources
Scalemetrics helps Swiss SMEs act on decisions like this before market conditions shift. Our company valuation services and outsourced CFO team give finance directors the senior expertise to move first.
Frequently Asked Questions
What should Swiss SMEs know about the Bid-Ask Spread is Reversing Founders' increasing demand for venture funding has outpaced the capital available from VC firms. This has led to a reversal in the bid-ask spread, with founders feeling their startups are undervalued, while limited partners (LPs) believe early-stage businesses are overvalued. As a result, mergers and acquisitions (M&A) and private equity deals are expected to see an uptick in 2024. Valuations are Facing Downward Pressure VCs and founders are grappling with differing perceptions of startup valuation. While founders feel their startups are undervalued, LPs express concerns about the overvaluation of early-stage businesses. This discrepancy is leading to a cautious approach from investors, with an increased focus on profitable markets, cost-cutting measures, and tighter efficiencies. VC Funds Experience Temporary Negative Returns In 2023, VC funds reported multiple negative returns for the first time in over five years. While experienced VCs consider this a natural correction, newcomers find it unique and daunting. Navigating this challenging environment requires strong investor relations and data analysis skills to make informed decisions. VC Due Diligence Gains Importance VCs are recognizing the need for thorough due diligence to scrutinize potential targets closely. This shift comes after a period of loose due diligence during a spending spree. Patient VCs will rely on traditional benchmarks and reliable data to assess valuations accurately. The European VC Market in 2024 2023 witnessed a decline in VC activity compared to previous years due to various economic factors such as the war in Ukraine, global supply chain issues, rising interest rates, inflation, and the possibility of a recession. The number of deals and capital invested decreased, and valuations faced downward pressure, particularly for late-stage companies. Fundraising Decline and Shift in Exit Activity Fundraising activity slowed down in the second half of 2023 due to market uncertainty. Exit activity experienced a significant drop, with a shift toward mergers and acquisitions accounting for 50% of VC-backed exits. Young startups opted for M&A transactions to secure greater financial certainty within established and well-capitalized businesses. Q1 2024: Decline in Deal Activity and Fundraising In Q1 2024, European venture deal value decreased by 32.1% quarter-over-quarter, accompanied by a 19.2% decline in the number of deals. High inflation and tightening monetary policy led investors to deploy less capital and focus on capital efficiency. Debt rounds are expected to become more common alongside equity rounds, leading to potential layoffs and cost-cutting measures within startups. Chart: European Venture Deal Value (Q1 2023: Q1 2024) Quarter Deal Value (EUR billions) Number of Deals Q1 2023 15.2 900 Q2 2023 13.0 850 Q3 2023 12.5 800 Q4 2023 10.3 750 Q1 2024 7.0 600 Outlook for Q2 2024 Q2 2024 is expected to be another challenging quarter for VC investment in Europe. Uncertainty in the market will likely make VC investors cautious, emphasizing the evaluation of business models for resilience and cost reduction measures within portfolio companies. Well-capitalized corporates may see this environment as an opportunity for acquisitions. Governments may increase support for startups, and non-core carve-outs and bolt-on deals may experience an uptick if market challenges persist. Technology Adoption in VC Firms In response to the challenging market conditions, VC firms are increasingly adopting advanced technologies to enhance their operations. Technologies such as artificial intelligence (AI) and machine learning are being used to: Improve Due Diligence: AI can analyze vast amounts of data quickly, identifying potential red flags and opportunities more efficiently than traditional methods. Enhance Deal Sourcing: Machine learning algorithms can identify promising startups by analyzing market trends and startup performance metrics. Optimize Portfolio Management: AI-driven tools can help VCs manage their portfolio companies more effectively, providing insights into performance and suggesting improvements. Impact of Economic Factors on VC Valuations Several economic factors are impacting VC valuations in Europe: Inflation: High inflation rates increase the cost of capital, making investors more cautious and leading to lower valuations. Interest Rates: Rising interest rates make debt financing more expensive, which can reduce the amount of capital available for equity investments. Geopolitical Uncertainty: Ongoing conflicts and geopolitical tensions create uncertainty, affecting investor confidence and leading to more conservative valuations. Strategies for Startups to Navigate the VC Landscape?
Scalemetrics helps Swiss SMEs act on decisions like this before market conditions shift. Our company valuation services and outsourced CFO team give finance directors the senior expertise to move first.
Company Valuation Switzerland: Methods That Swiss Banks and Investors Actually Accept
Getting company valuation Switzerland right matters whether you are raising capital, planning a partial exit, onboarding an employee stock option plan (ESOP), or simply trying to understand what your business is worth before making a strategic decision. In Switzerland, the most widely accepted valuation methodologies for private SMEs are: (1) the Practitioner Method (Praktikermethode) – a weighted average of earnings value and net asset value, used by cantonal tax authorities for inheritance and gift tax purposes; (2) the DCF method, required for financing and M&A discussions; and (3) the market multiples approach, where Swiss transaction data from comparable sales provides the reference range. The choice of methodology materially affects the result, and sophisticated counterparties – banks, investors, co-shareholders – will scrutinise both the method and the underlying assumptions.
Common mistakes in company valuation Switzerland include: using a single-year EBITDA that includes non-recurring items rather than a normalised three-year average; applying US or UK public market multiples to a Swiss SME without a size and liquidity discount (typically 20-35%); and ignoring minority discount or control premium adjustments when the valuation is for a partial stake. Scalemetrics prepares independent valuation reports for Swiss SMEs in formats accepted by ESTV, Swiss cantonal courts, Hausbanken, and Series A/B investors. If you need a defensible, professionally documented company valuation with explicit methodology disclosure, we can deliver it within 10-15 business days for most SME mandates.
What financial services does Scalemetrics provide for Swiss SMEs?
Scalemetrics provides Swiss SME owners and CFOs with practical financial expertise: from accounting and tax compliance to financial planning, KPI monitoring, and on-demand CFO services. The goal is to give growing businesses access to senior financial leadership without the cost of a full-time hire.
When does a Swiss SME need a fractional CFO?
A fractional CFO becomes valuable from around CHF 1-2M in annual revenue, or ahead of specific events: bank financing applications, investor rounds, M&A, or rapid growth phases. The cost is a fraction of a full-time CFO salary, with expertise available immediately.
How does Scalemetrics differ from a traditional Swiss fiduciary firm?
Traditional fiduciary firms focus on tax compliance and year-end accounts. Scalemetrics adds strategic financial leadership: rolling forecasts, cash flow modelling, KPI dashboards, and financing advisory – delivered as an ongoing mandate or for a specific project.
Which Swiss cantons does Scalemetrics cover?
Scalemetrics serves clients across Switzerland, with particular depth in Zürich, Zug, Basel, and Bern. Digital delivery means canton-independent collaboration, with expertise in cantonal tax rates, AHV structures, and local banking relationships.
Sources & References
The Shifting Landscape of European Venture Capital Valuations in 2026
European venture capital markets entered 2026 in a period of recalibration following the valuation correction that began in late 2022. The era of near-zero interest rates — which had inflated growth-stage multiples to historic highs — has given way to a more disciplined pricing environment. For Swiss SMEs and growth companies seeking institutional capital, understanding these valuation trends is no longer optional; it is a prerequisite for entering investor conversations with credible expectations.
At the seed and Series A level, European investors are applying greater scrutiny to unit economics than at any point in the past decade. Revenue multiples for SaaS and technology businesses that commanded 20–30x ARR at peak are now frequently priced at 5–10x for high-quality assets, with secondary-tier businesses seeing multiples compress further. The Swiss market, while benefiting from the stability of CHF-denominated revenues and the strength of the broader Swiss business environment, is not immune to these trends — particularly for companies seeking cross-border institutional capital.
The BVG reform, enacted in 2024 and progressively implemented through 2025–2026, has also affected the employment cost structures that investors model when evaluating Swiss growth companies. With BVG contributions ranging from 8–12% of insured salary depending on age bracket, Swiss-based businesses carry higher loaded labour costs than comparable German or UK counterparts — a factor that sophisticated investors now explicitly model in their return scenarios.
What Swiss Growth Companies Must Demonstrate to Attract Institutional Capital
The investors deploying capital into European venture in 2026 are predominantly applying a "Rule of 40" lens — the principle that a company's revenue growth rate plus its EBITDA margin should exceed 40%. This framework, borrowed from public market analysis, has become a standard filter even at early growth stages. Swiss SMEs that cannot demonstrate a credible path to Rule of 40 compliance will find institutional fundraising considerably more challenging than their predecessors did in 2020–2021.
Beyond the headline metric, investors are focusing on three areas: gross margin quality, capital efficiency, and management team depth. In the Swiss context, gross margin quality is particularly relevant for professional services-adjacent businesses, where blended margins of 40–60% are common but less compelling than pure-software margins of 70–80%. Capital efficiency — measured by metrics such as burn multiple (net burn divided by net new ARR) — has replaced growth-at-all-costs as the dominant investor framework.
European VC Valuation Benchmarks: 2024 vs. 2026
| Stage | Revenue Multiple (2024) | Revenue Multiple (2026) | Key Investor Focus |
|---|---|---|---|
| Seed | Pre-revenue / concept | Pre-revenue / concept | Team, market size |
| Series A (SaaS) | 8–12x ARR | 5–8x ARR | NRR, CAC payback |
| Series B (SaaS) | 10–15x ARR | 6–10x ARR | Rule of 40, burn multiple |
| Growth (B2B services) | 3–5x revenue | 2–4x revenue | EBITDA margin, retention |
For Swiss SMEs preparing to raise institutional capital, building the financial infrastructure to credibly present these metrics — clean management accounts, cohort analysis, KPI dashboards — is as important as the commercial story. Our investor readiness service helps Swiss growth companies translate their operating performance into the language institutional investors require.

Pascal Stämpfli leverages over a decade of expertise in corporate finance and venture capital to scale and optimize businesses. A CFA charterholder with a Master's in Economics from the University of St. Gallen, Pascal specializes in market & company assessments, strategy, and business value creation. Having assessed more than 1,000 companies for financial and strategic investors provides him with a sophisticated understanding of investor rationale and capital allocation. As the Managing Director of Scalemetrics and Managing Partner at COREangels Big Data & AI Europe, Pascal operates at the intersection of financial discipline and technological innovation.